Tax
How is the ESPP discount taxed?
Quick Answer
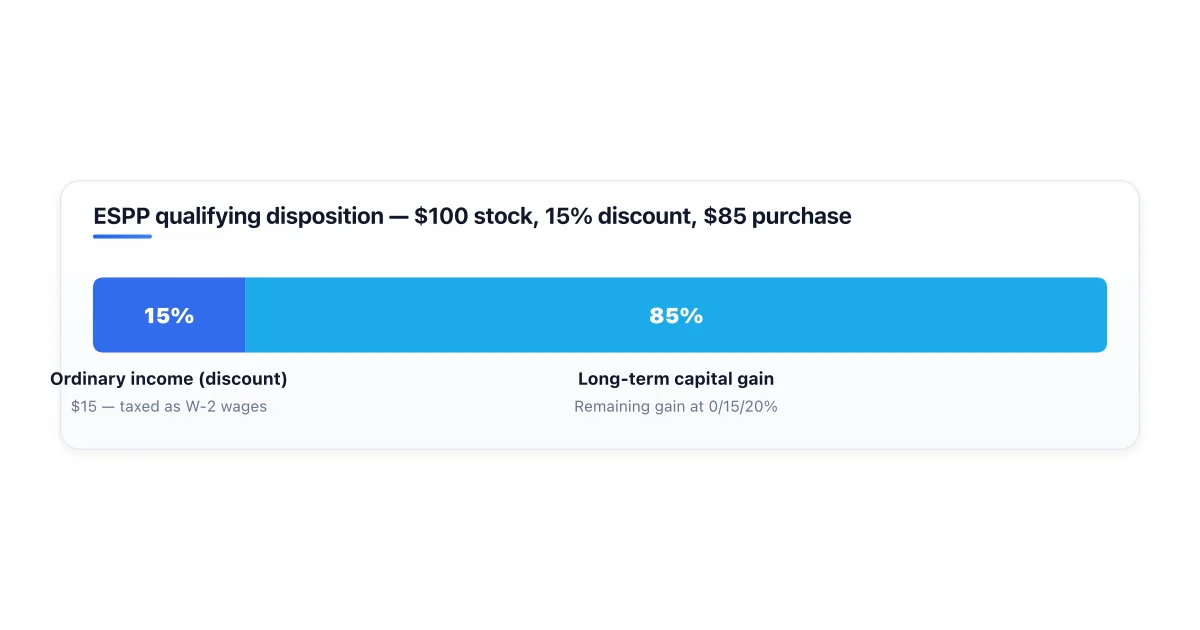
A qualified Section 423 ESPP defers tax until you sell — the 15% discount becomes ordinary W-2 income and additional gain is capital. Qualifying dispositions (>2yr from offering, >1yr from purchase) cap ordinary income at the actual discount.
Warren Team
Updated April 26, 2026
37
Warren Team
Updated April 26, 2026
37
Important Disclaimer:
The information provided is for educational purposes only and should not be considered as personalized financial advice. Warren is a registered investment advisor. Past performance does not guarantee future results. Please consult with a qualified financial advisor before making investment decisions.
Get Personalized Advice
Schedule a free 15-minute consultation with our fiduciary advisors
Book Free Consultation